Know the date your home is yours, and what it frees next.
Your Freedom Plan puts real dates on the road to owning your home outright, from your own figures. Your finance specialist goes through it with you, and looks again every year.
Six dates, one road to owning your home
Every Freedom Plan follows the same six stages. Each has a date on your plan and one person who owns it.
Step 1: Start
Your plan is written from your own figures: your balance, repayment, term and buffer. You read it with your finance specialist on a call.
Step 2: Buffer
Cash set aside first, so extra repayments never leave you short. The plan shows the amount to hold before you pay more.
Step 3: Under 80 per cent
The month your loan falls below 80 per cent of your property value, on your repayments alone. LVR is your loan as a share of that value. We ask your provider for a rate review.
Step 4: Under 75, then 70 per cent
The next two dates, each dated on the plan, with the same step: a rate review, or a refinance compared with the cost of moving.
Step 5: Equity open
When there is room to move, your finance specialist explains the finance side. What to do with that room is a conversation with an authorised adviser.
Step 6: Annual review
Once a year your finance specialist looks again. They check where your LVR stands, what your provider offers and your buffer, then update your plan and the next date.
See the plan before you book
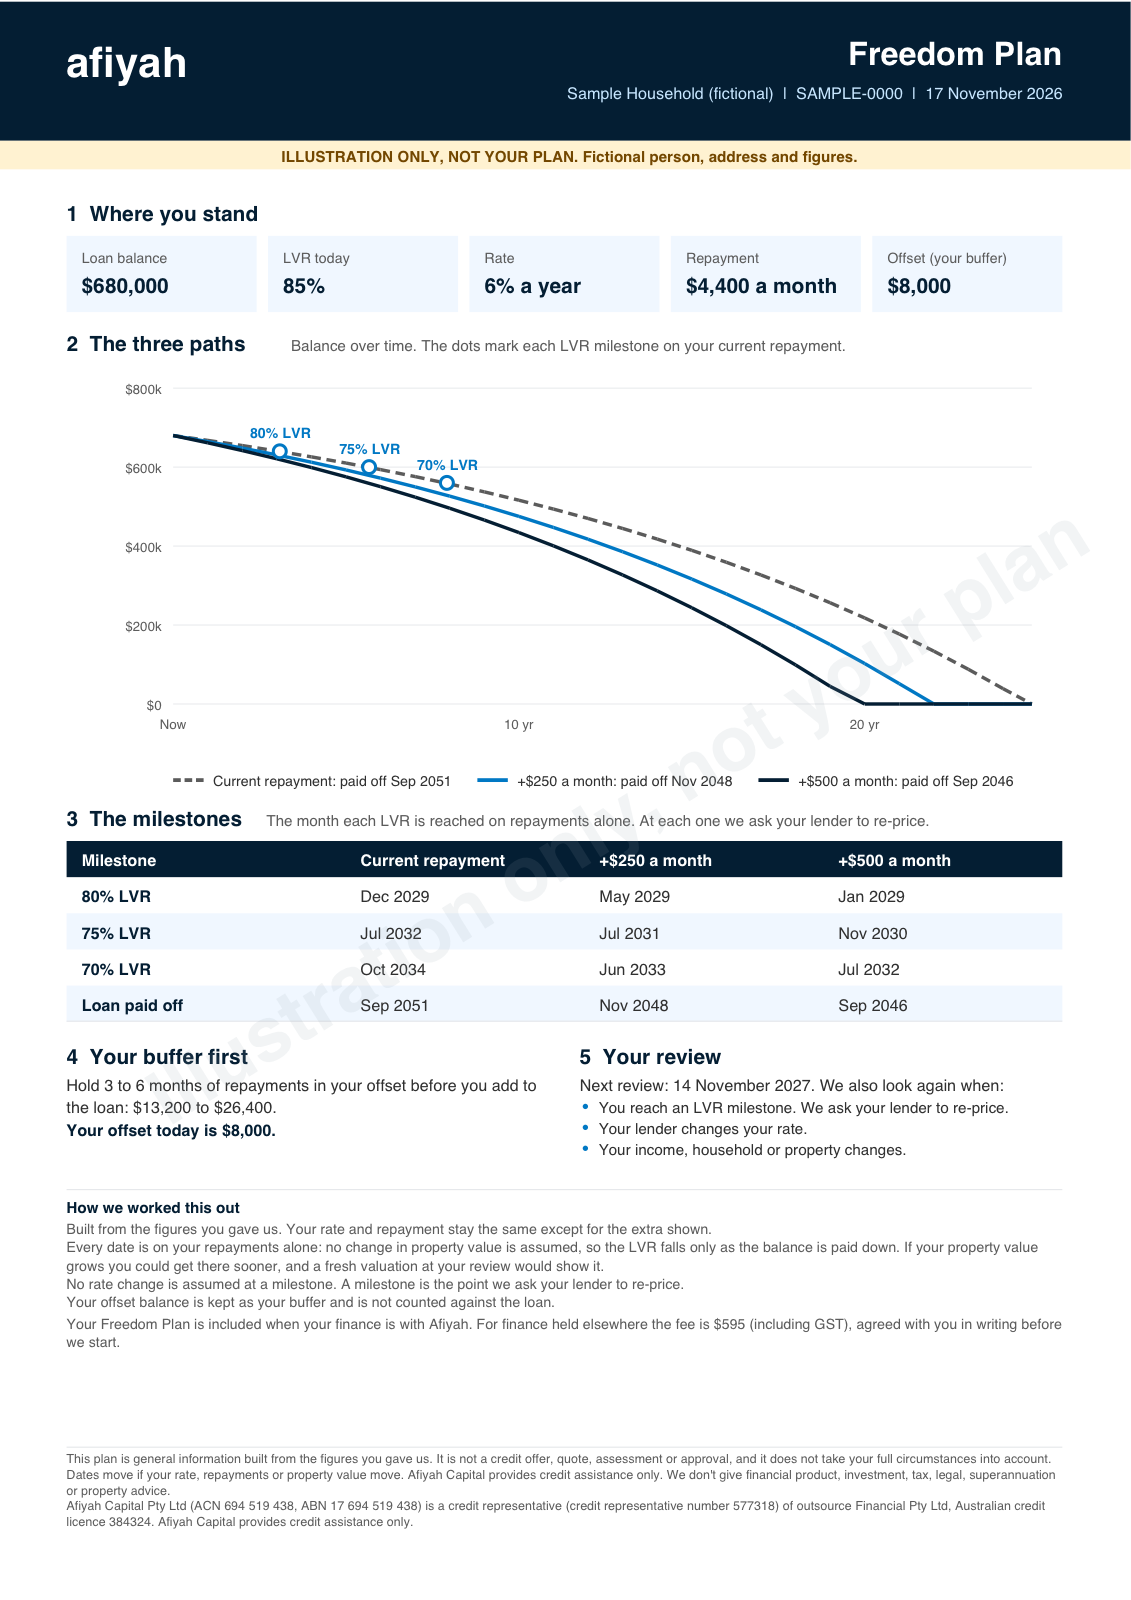
One page: your balance, three repayment paths on one chart, and the month you reach each milestone. This sample uses a fictional household.
Two ways to have a Freedom Plan
Start with the plan. Add advice when there is room to move.
- Freedom Plan
- The written plan as a PDF, with your dates at 80, 75 and 70 per cent and your buffer target. The plan is in your Afiyah portal. You also get a yearly review with your finance specialist.
- Freedom Plan + Advice
- The Freedom Plan, plus the step after it: once there is room to move, an authorised adviser helps you decide what it does next.
Finance held elsewhere
- Freedom Plan
- The same written plan for finance you hold elsewhere, built from the statements you share: your dates and your buffer target.
- Freedom Plan + Advice
- That plan, plus an authorised adviser for the step after it.
Once a year, we look again
A plan only works if it keeps pace with your life. The yearly review is how it does.
- Your LVR
- Where you stand against the 80, 75 and 70 per cent dates, on a fresh property value.
- Your provider
- A rate review request, or a refinance compared with the cost of moving, if one is worth making.
- Your buffer
- Whether it is at target before anything extra is paid.
- Your plan
- Updated, with the next review date. A change in your income, household or property can bring it forward.
Where does a Freedom Plan start?
Four common starting points. If yours is different, say so when you book.
- I pay the minimum and have no plan for the termYour finance is a few years old and the end date is a long way off. A plan puts dates on it.
- I want my next finance to have a plan from day oneStarting or moving finance, you want a way to finish sooner, not thirty years and hope.
- I run a business and my income changesLumpy income needs a buffer before extra payments. The plan puts the buffer first.
- I want my home to stop being the whole planThe finance comes first. The plan then shows when money is freed, and an authorised adviser helps with what it does next.
If payments are already hard, tell your provider early. That is a different conversation, and it comes first.
Plain questions
Is the Freedom Plan financial advice?
No. The plan is credit assistance about your finance: its structure, cost and timing. What to do with the money it frees is a conversation with an authorised adviser.
Does my finance have to be with Afiyah?
No. We can write a plan for finance held elsewhere. The fee is $595, including GST, and we agree it with you in writing before we start.
What do you need from me?
Your latest finance statement and a recent property value. We also ask about your term remaining, any offset balance and your other debts.
Will the plan always say to pay extra?
No. Sometimes the answer is to build the buffer first, or to wait for a fixed period to end. The plan says so, with the dates.
What if my finance is Islamic finance?
The plan works from your payment schedule. Providers differ on extra payments and rate reviews, so we confirm your provider’s terms before a date goes on the plan. A milestone is a prompt to ask for a rate review.
Do the dates promise a result?
No. They come from the balance, rate, repayment and property value you give us, and move if one changes. The plan never quotes a rate or a return.
Certificate of Shariah Compliance No. ADL00430526, issued by Adl Advisory Sdn. Bhd. on 18 May 2026 and valid to 17 May 2027. It covers Standard Ijarah Home Financing only, for new contracts from 18 May 2026, and is not a religious ruling. Our Shariah governance
Want dates, not guesses?
Book a call. Your finance specialist goes through your balance, repayment and property value with you.